4 Tips for Organizing Your Business Financials (and One Tool That Will Really Help)

Organizing your small business financials doesn’t have to be a daunting task. By following a few simple steps, you can create a system that works for you and your business.

Step 1: Take Time to Plan

Decide what information you need to track and how you’re going to track it. There’s no right or wrong way to do this—it all depends on what’s best for your business. Create a budget and track your expenses using a spreadsheet or app. This will help you stay on top of your spending and make sure you’re not overspending on unnecessary things.

Step 2: Separate Your Bank Accounts

Setting up separate bank accounts for your business and personal expenses. Keeping business and personal accounts separate will help you to see what income and expenses are truly for the business and provide valuable information to make decisions.

Step 3: Reconcile Your Accounts

Start reconciling your accounts on a regular basis. This will help you keep track of expenses and income and ensure your books are up to date.

Step 4: Create a Bill-Paying System

Put together a bill-paying system that works for you. This may involve setting up automatic payments or simply creating a list of bills to be paid each month. There are several software programs that can help with this—Bill.com, Veem and Melio are just a few.


By taking the time to organize your small business finances, you can save yourself time and money in the long run.

One Tool in a Sea of Many to Help You Get Organized

QuickBooks Online is a great tool for small business owners who want to get their finances in order. QBO can help you track expenses, reconcile your accounts, and create a bill-paying system that works for you. 


QuickBooks Online can also help you plan for your future by creating financial projections, developing budgets and tracking your progress over time. It is a powerful tool that enables you to take control of your finances and run your business more effectively. 


Not sure you want to try it alone? Reach out to us we can evaluate your business needs and recommend the right QuickBooks Online subscription. We can also provide training to get you started organizing your business.

Our Latest Insight

By Alisa McCabe September 14, 2026
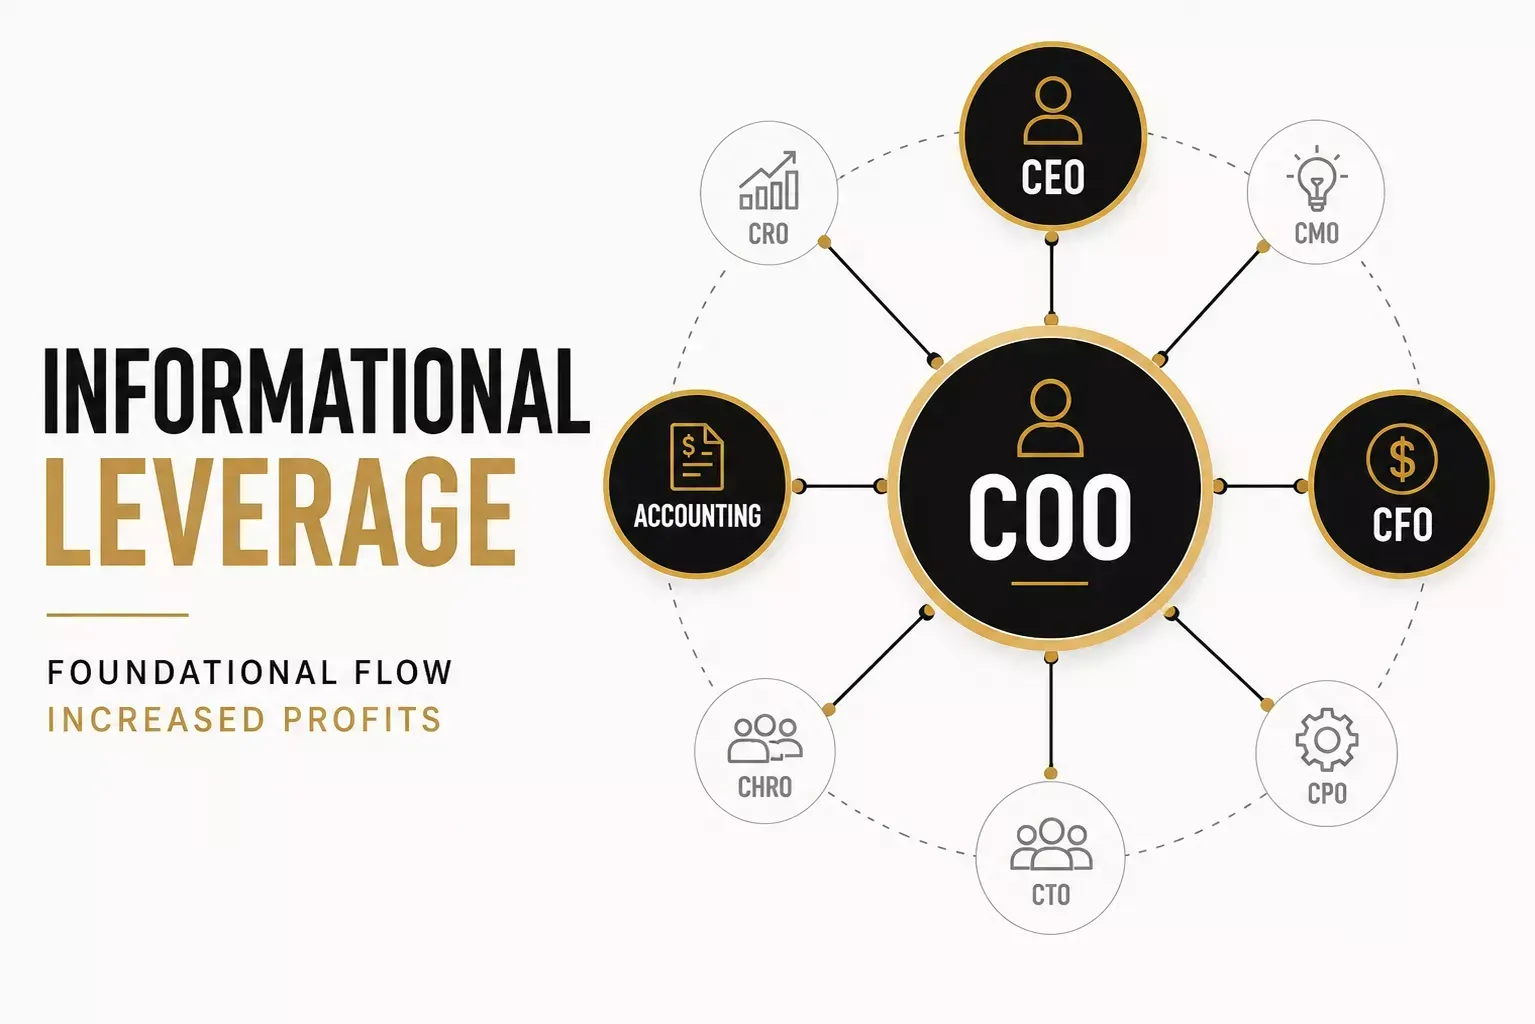
"Accounting is a stick in the mud." "I'm not really sure what a COO does all day." "The CFO just plays around with their little Excel sheets." You have probably heard one of those lines. You may have thought one yourself. They sound like harmless office humor. They actually point to something expensive. In most growing service businesses, nobody has ever defined how operations and accounting work together. The people who produce your financial reports sit outside the very decisions those reports are meant to inform. That gap costs you every single month, quietly, in profit that should have been there.  ​ Part 1 of a 5-part series on the COO and Accounting relationship
By Alisa McCabe September 14, 2026
In modern business management, effective capacity planning requires far more than matching supply with demand—it demands a rigorous financial framework. Every unit of unused capacity represents sunk cost and margin erosion, while every unit of insufficient capacity risks churn and missed revenue. By evaluating capacity planning as a financial exercise, organizations can translate labor hours, utilization rates, and operational throughput into clear financial metrics like cost of goods sold (COGS) and return on invested capital (ROIC). This guide explores how to integrate operational capacity into your financial planning and analysis (FP&A) cycle to drive sustainable, cash-efficient scale.
By Alisa McCabe August 31, 2026
In a service-based business, time is literally money, and every day an invoice goes unpaid, your margin shrinks. Unlike product businesses that can rely on physical inventory to back up value, service providers face a unique cash flow vulnerability: you've already delivered the work, paid your team, and covered overhead long before the client settles the bill. That makes managing your Accounts Receivable (AR) aging schedule critical to survival. But how do you know if your outstanding invoices are normal or a sign of trouble?  Understanding key AR aging benchmarks, and where your service business stands relative to industry standards, is the first step toward reclaiming your cash flow and protecting your bottom line.This article walks you through the 30-60-90 AR Health Check and what healthy numbers look like for your business.

CONTACT US

Contact Us