Your Guide to Successful Tax Planning for Your Small Business

As a small business owner, you know it’s important to keep your finances in order. But did you know tax planning is one of the most important aspects of financial management? Unfortunately, many small business owners don’t do any tax planning at all. This can lead to big problems down the road.


In this blog post, we will discuss why tax planning is so important for small businesses, and we will also give you some tips on how to prepare for a successful tax planning session.

Why Tax Planning?

There are several reasons tax planning is so important for small businesses. First of all, it can help you save money. By planning your taxes ahead of time, you can ensure you are taking advantage of all of the deductions and credits you are entitled to. This can lead to a significant reduction in your tax bill.


We strongly recommend having a tax planning meeting with your CPA in October or November to take advantage of the actions your CPA suggests. If you are part of our virtual CFO services, your vCFo will attend the tax planning meeting and help implement those actions.


Tax planning can also help you avoid problems with the IRS. If you don’t take the time to plan your taxes, you may end up making mistakes that could trigger an audit. By taking the time to do some tax planning, you can avoid these potential problems.

Tips for Tax Planning Success 

Now that you know why tax planning is so important, what do you need to do to have a successful tax planning session? The first step is to gather all the information you will need. This includes your income statements, receipts, and any other documents that will be relevant to your taxes. If you are working with First Steps Financial, your dedicated accounting support will be able to provide all the reporting you and your CPA will need.


There are a few different ways to approach tax planning. You can do it yourself, or you can hire a professional tax planner. If you decide to do it yourself, there are a few resources that can help you. The IRS website has a lot of great information on tax planning, and there are also many software programs.


If you decide to hire a professional tax planner, make sure you choose someone who is reputable and who has experience working with small businesses. If you need references for a CPA, we can provide a list of CPAs we recommend.


No matter how you do it, tax planning is an important part of financial management for any small business. By taking the time to plan ahead, you can save yourself money and avoid potential problems with the IRS.


Don’t wait until tax season to start planning! Now is the time to get started.

Our Latest Insight

By Alisa McCabe • September 28, 2026
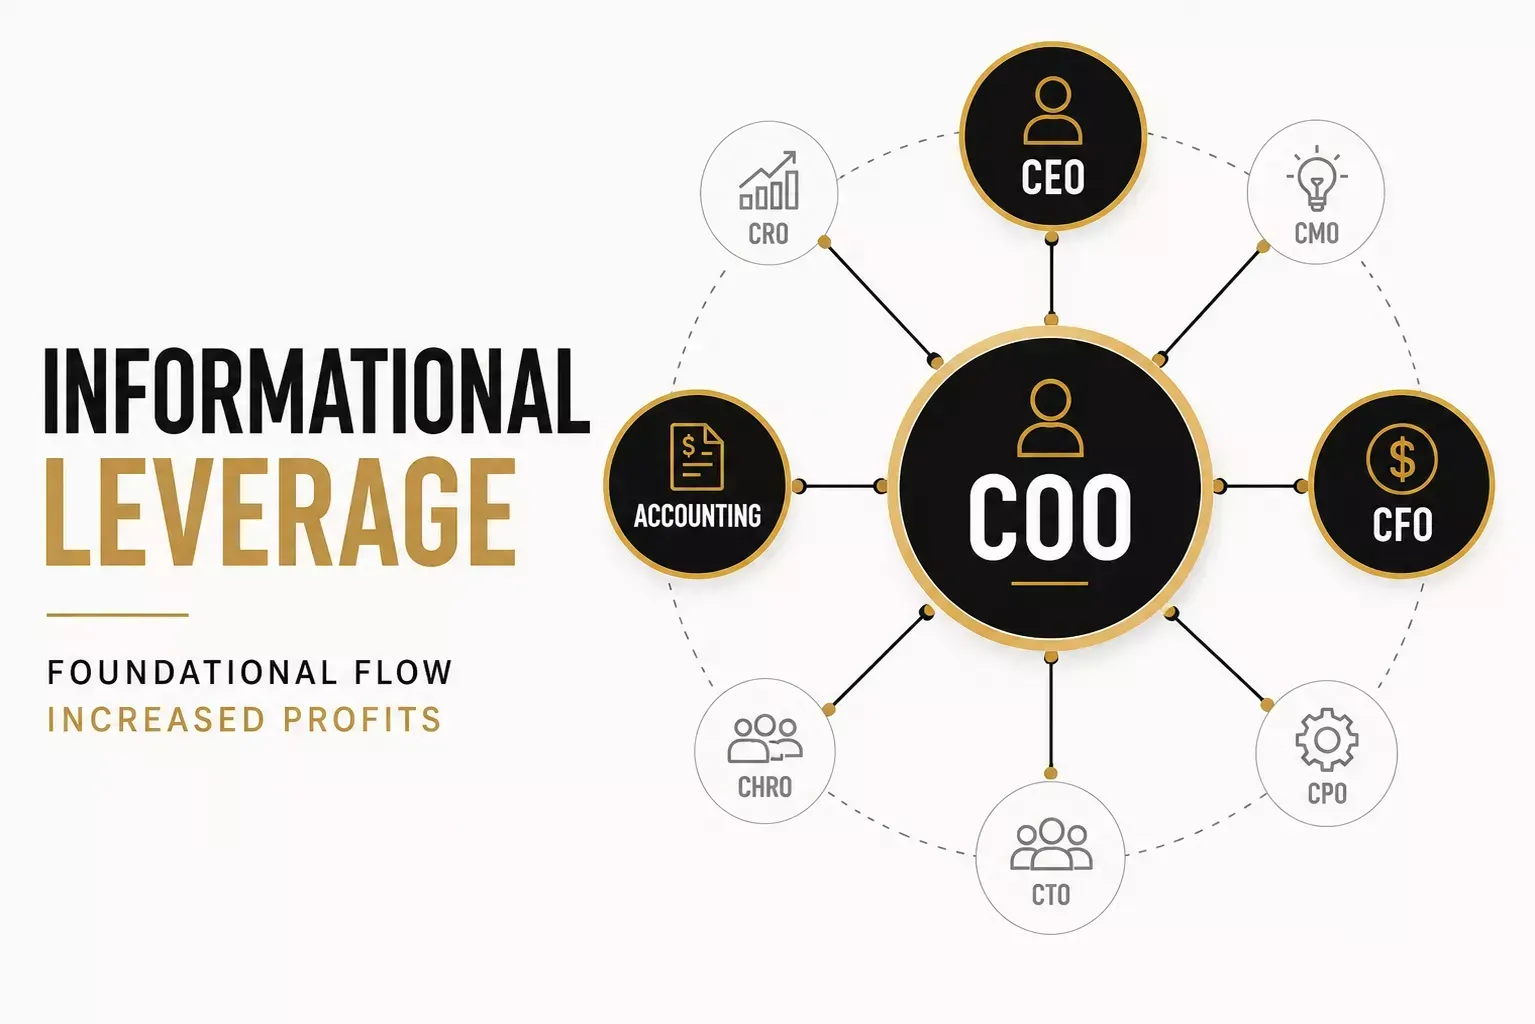
Article 2 ended with a question. What would you actually see first if this relationship started breaking down inside your business? Here is the answer. You would see five things. If you are like most owners reading this, you are already looking at two or three of them. None of the five announces itself as a communication problem. Each one shows up as friction inside your accounting systems, wearing a perfectly reasonable disguise. That is the difficulty. On the surface, none of these looks like a broken relationship. Each looks like something else entirely. A busy month. A tough quarter. A personality difference between two people who were never going to be friends anyway. Every one of them gets explained away the first time you see it. That is exactly what makes them expensive. This article does not fix any of it. Article 4 does that. The job here is naming what is already sitting in front of you. Most owners walk past these signs for years without recognizing what they are looking at.  ​ Part 3 of a 5-part series on the COO-Accounting relationship
By Alisa McCabe • September 21, 2026
Article 1 ended with a question. When does your COO actually talk to Accounting before a decision gets made? How long did it take you to answer? Immediately? Minutes? Maybe you could not think of a single example. Bills get paid, projects keep moving, and financial reports show up. Nothing feels obviously broken, so you conclude everything is fine. If that question made you uncomfortable, you are not alone. Here is the part that keeps this problem alive. You only know what good looks like based on what you have already lived through. Most owners have never worked inside a business where Operations and Accounting were intentionally built to function together. So they measure their company against their own status quo. This article gives you a different reference point. You will see what the relationship looks like day to day, what rhythm it runs on, and five things you can check this week. None of it requires scrapping what you have built. The people are already in the building. The data already exists. What changes is how the pieces are arranged, and how much leverage you get out of the company you have right now.  ​ Part 2 of a 5-part series on the COO-Accounting relationship
By Alisa McCabe • September 14, 2026
"Accounting is a stick in the mud." "I'm not really sure what a COO does all day." "The CFO just plays around with their little Excel sheets." You have probably heard one of those lines. You may have thought one yourself. They sound like harmless office humor. They actually point to something expensive. In most growing service businesses, nobody has ever defined how operations and accounting work together. The people who produce your financial reports sit outside the very decisions those reports are meant to inform. That gap costs you every single month, quietly, in profit that should have been there.  ​ Part 1 of a 5-part series on the COO and Accounting relationship