Business Savings Emergency Fund: How Much Should You Keep in Cash Reserves?
Unexpected disruptions happen to every organization, no matter how established it may feel. Equipment breaks, clients delay payments, or market conditions tighten without warning. That uncertainty is why a dedicated cash buffer matters. A well-structured business savings emergency fund provides stability during uneven periods and helps leadership make decisions calmly rather than reactively.
Still, many owners ask the same question. How much liquidity is enough without letting idle funds hold the company back?
Still, many owners ask the same question. How much liquidity is enough without letting idle funds hold the company back?
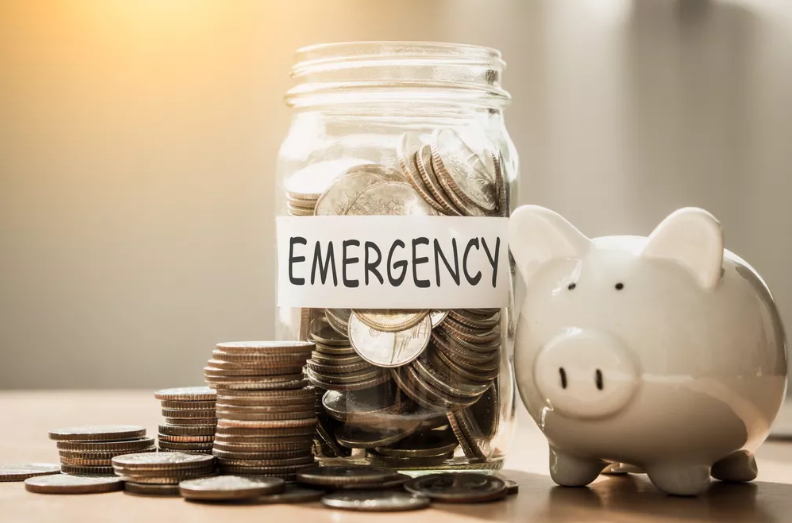
Why an Emergency Fund Is a Financial Anchor
An emergency reserve exists to protect daily operations when income timing shifts or expenses spike. Unlike growth capital, this money is not meant for expansion, hiring, or upgrades. Its purpose is continuity.
Having accessible business savings allows payroll, vendor obligations, and essential overhead to continue even during short-term stress. That breathing room preserves relationships and credibility, which can be difficult to rebuild once damaged.
Just as important, it reduces emotional decision-making. Leaders with a cushion can pause, assess options, and choose the most strategic path forward rather than acting out of urgency.
How to Calculate the Right Reserve Size
There is no universal number that fits every company, but a common benchmark is three to six months of core operating costs for business savings. Start by identifying predictable outflows such as compensation, rent, utilities, software subscriptions, and insurance.
Next, evaluate revenue reliability. Organizations with steady contracts may lean toward the lower end of the range. Those with seasonal income or client concentration often benefit from a larger buffer.
Also consider access to external funding. If credit lines are limited or expensive, holding more liquidity internally can provide flexibility when timing gaps appear.
Where to Keep Your Cash Reserves
An emergency fund should be easy to access and separate from daily transaction accounts. Mixing reserve money with operating cash increases the temptation to use it for nonessential purposes.
Many companies choose high-yield business savings or money market accounts that preserve principal while earning modest returns. The goal is safety and availability, not aggressive growth.
Clear labeling and internal guidelines help reinforce the purpose of the fund so it remains untouched unless a true disruption occurs.
Common Mistakes to Avoid
One frequent misstep is building business savings but never revisiting the amount. As operations scale, expenses rise, and your client mix changes, the business budget should be adjusted accordingly.
Another issue is using the fund as a convenience account. Tapping reserves for planned purchases defeats its protective role and can leave the organization exposed when an actual emergency arises.
Finally, some owners delay building reserves entirely because margins feel tight. Starting small and contributing consistently is far more effective than waiting for a perfect moment.
Building Confidence With the Right Financial Guide
Determining the appropriate reserve level and maintaining it over time requires visibility into cash flow patterns and expense behavior. This is where First Steps Financial
can serve as a steady guide. Through fractional bookkeeping and financial consultation, our team helps organizations understand real operating needs, set realistic reserve targets, and monitor progress without adding internal complexity.
If you want clarity around cash reserves and long-term financial resilience, let’s connect.
Our Latest Insight
There is a frustrating stage of growth when the business makes more money and becomes harder to run. You expected growth to create leverage. Instead, your calendar is fuller and decisions take longer. Projects compete for the same people. Expenses become harder to explain. Accounting needs more information from Operations. Operations needs more information from Accounting. And the accounting systems that carried you to $2 million were not built for $15 million. Nothing necessarily looks broken. That is what makes this stage so deceptive. The processes that got you here may still work. Your people may still be good. Your customers may still be buying. What changed is the weight your existing structure is being asked to carry. At $2 million, you can still personally compensate for the gaps. Somewhere on the road to $5 million, $10 million, or $15 million, that stops being possible. The business did not suddenly become dysfunctional. It outgrew its dependence on informal coordination. Part 5 of a 5-part series on the COO-Accounting relationship
If Article 3 felt a little too familiar, your first instinct may be to call a meeting. You tell Operations and Accounting they need to communicate better. That will not fix it. The five warning signs were never personality problems. They were signs that your accounting systems and routines were never intentionally built around how these two functions work together. People cannot follow a structure that does not exist. Accounting cannot inform decisions they do not know are being considered. Your COO cannot use financial information they cannot access in time. The fix is not complicated. That does not mean it happens naturally. Most of what you need to build will feel almost obvious. Recurring conversations. Clear handoffs. Shared definitions. Access to the right information. This is not glamorous work. That is probably one reason it gets overlooked. For the first few months, you may have to follow up constantly. People will forget. Meetings will get moved. Someone will make a decision and skip the handoff. Then something starts to change. The follow-up becomes unnecessary. Information moves without you. Problems get caught earlier. Eventually the results look effortless from the outside. They were not. You built the relationship that made them possible. Part 4 of a 5-part series on the COO-Accounting relationship
Article 2 ended with a question. What would you actually see first if this relationship started breaking down inside your business? Here is the answer. You would see five things. If you are like most owners reading this, you are already looking at two or three of them. None of the five announces itself as a communication problem. Each one shows up as friction inside your accounting systems, wearing a perfectly reasonable disguise. That is the difficulty. On the surface, none of these looks like a broken relationship. Each looks like something else entirely. A busy month. A tough quarter. A personality difference between two people who were never going to be friends anyway. Every one of them gets explained away the first time you see it. That is exactly what makes them expensive. This article does not fix any of it. Article 4 does that. The job here is naming what is already sitting in front of you. Most owners walk past these signs for years without recognizing what they are looking at. Part 3 of a 5-part series on the COO-Accounting relationship