Materials COGS Tracking for HVAC, Plumbing, and Electrical Contractors
Most trade contractors know their revenue down to the dollar. Ask them what materials actually cost on last month's jobs, and the answer gets fuzzy. That gap is where profit quietly disappears. Solid contractor accounting starts with knowing what you spent on pipe, wire, fittings, and equipment for each specific job. Not for the month. Not for the quarter. For the job.
When materials costs sit in one giant bucket, you lose the ability to see which work makes money and which work drains it. This guide walks through the Materials COGS Playbook, a practical framework for getting materials tracking right in HVAC, plumbing, and electrical businesses.
Contractor Accounting: Why Materials Costs Slip Through the Cracks
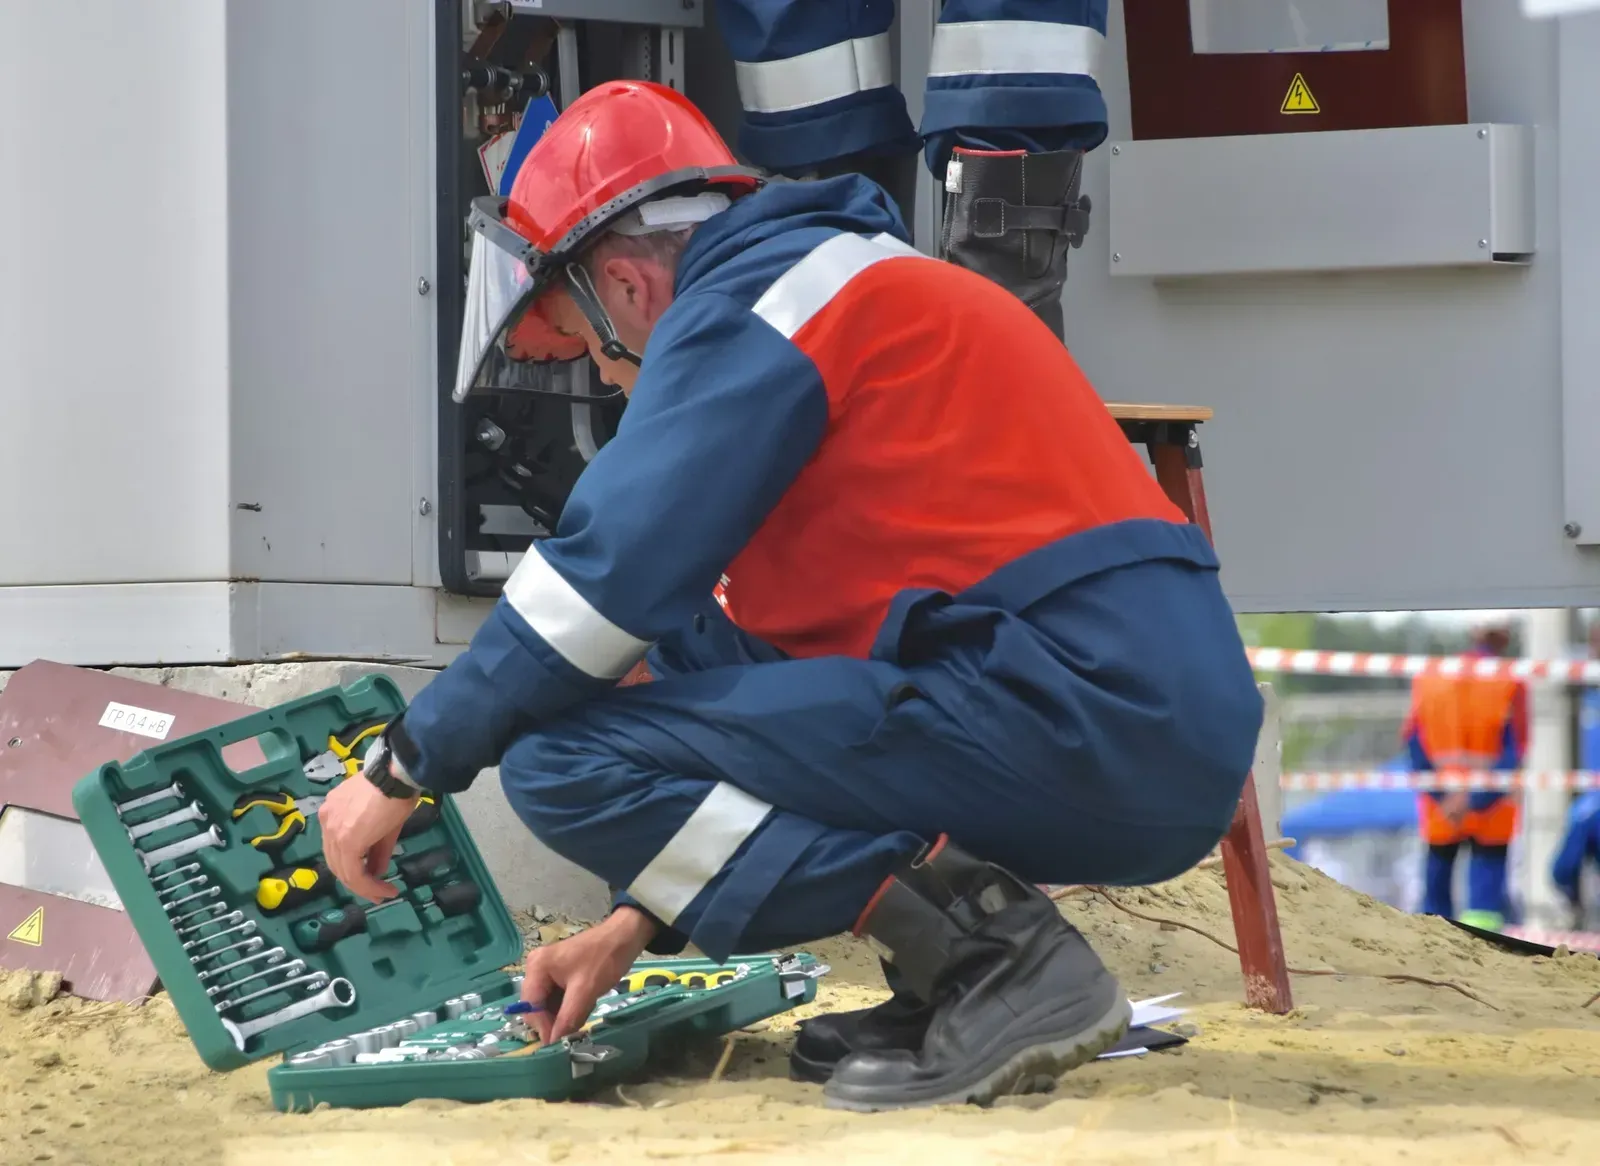
Field operations move quickly. A technician might stop by the supply house first thing in the morning, pick up required materials, and charge it to a company card. When the job number is left off, that receipt ends up dumped into a general "Supplies" expense account, instantly skewing your job profitability tracking.
Multiply that by six trucks and twenty jobs a week. The distortion compounds quickly.
Here is what usually causes the breakdown:
- Purchases coded to a general expense account instead of job-level materials COGS
- Supply house invoices billed to the account with no purchase order reference
- Materials pulled from truck stock or the warehouse and never assigned to a job
- Returns and credits that never get matched back to the original job
- Change order materials absorbed into the original job cost without a price adjustment
None of these are accounting failures on their own. They are workflow gaps. Good contractor accounting closes those gaps before the numbers hit your financial statements.
The Contractor Accounting Materials COGS Playbook
Mastering job profitability doesn't require complex financial engineering; it comes down to executing a structured, repeatable process. Built specifically for trade contractors, this four-part framework establishes clear visibility over your materials COGS and strengthens your job-costing workflows. Here is how to put it into practice step by step:
1. Separate materials from everything else in your chart of accounts
Materials COGS should be its own line, distinct from subcontractor costs, labor burden, equipment depreciation, and fleet expense. Lumping them together hides the story. A plumbing job with high materials and low labor is a different business problem than the reverse.
2. Require a job number at the point of purchase
This is the single highest-impact change most contractors can make. The technician who buys the part is the only person who knows what job it is for. Capture it then, not three weeks later. Purchase orders, app-based receipt capture, and vendor accounts can all achieve this. Select the method that fits best and apply it consistently.
3. Match supply statements to job costs every month
Vendor statements from your electrical or HVAC distributor are your audit trail. Reconcile them against what landed in each job. Missing items show up fast. So do items billed twice.
4. Review materials as a percentage of revenue at the job level
This shift elevates tracking into true management. It exposes previously hidden trends, such as material-intensive job types, estimators who regularly undervalue parts, or client scope creep that erodes profit margins.
Run this playbook consistently for one quarter, and your job costing becomes something you can actually price from.
Where Job Costing Breaks Down in the Field
Even immaculate bookkeeping falls short if field workflows remain flawed. Trade businesses, in particular, must navigate several key operational vulnerabilities:
Unallocated Van Stock
Truck inventory represents the most frequent oversight. Parts sit on service vehicles for extended periods and get deployed across multiple projects without proper job tracking. Address this by conducting routine truck stock audits and assigning consumable items to projects using standard rates instead of writing them off as zero-cost items.
Timing Discrepancies in Billing
Extended installations and ground-up builds introduce significant cash flow delays. Material expenditures are recorded almost immediately, whereas project invoicing occurs weeks down the road. Retainage provisions delay these cash inflows even further.
As a result, your income statement can appear healthy while cash reserves run dangerously low. Advance payments present a comparable financial timing challenge. Review our detailed analysis on to master this accounting mechanism.
Callback and Warranty Services
Returning to resolve an issue with a faulty component uses up labor and materials without generating additional income. Assigning these expenses directly to the initial project inexplicably erodes your profit margins. Conversely, failing to track them entirely leaves you without insight into which installations trigger repeat visits.
What Accurate Materials COGS Reveals About Pricing
Clean job-level materials COGS completely changes how you approach pricing.
Instead of basing markups on competitor rates, you can price with complete certainty by accounting for true landed costs, including freight and minor miscellaneous items.
Spotting margin drift also becomes much easier. Material expenses shift over time as items like wire, fixtures, refrigerant, and copper fluctuate in price. Tracking costs at the job level exposes outdated markup percentages within weeks, preventing unexpected losses at the end of the year.
Estimating accuracy improves as well. Evaluating estimated versus actual material costs on finished jobs provides estimators with actionable insights. Highlighting trends, such as commercial work generating higher waste than residential jobs or rough-in work being consistently underbid, helps refine every subsequent bid.
Additionally, cash forecasting improves significantly. Understanding the standard ratio of material costs to overall contract value allows you to anticipate cash outflows before starting a project; a crucial advantage when managing multiple major jobs while awaiting progress payments.
Get Your Job Costs Working for You
You already run the crews, win the bids, and keep customers happy. You should not have to reverse-engineer your own margin from a stack of receipts. If your materials costs are living in one general expense account, you are making pricing decisions with incomplete information, and that is a hard way to grow.
At First Steps Financial, we have been the fully remote accounting department for service businesses since 2012. We understand how trade work actually makes and loses money. That means job costing built the way your business operates, monthly closes you can trust, and reporting that answers the questions you are actually asking.
Our fractional bookkeeping service handles the transaction detail, reconciliations, and AP/AR discipline that make job-level tracking possible. As you scale, controller-level reporting builds on that same foundation.
Let's talk about what your materials COGS is really telling you, and set up job costing that helps you price jobs with confidence.
Our Latest Insight