The Benefits of Narrowing Your Focus in Business

When it comes to business, most people think that the more markets they conquer, the better. But this isn’t always the case. In fact, specializing in one area of business can have a number of benefits for your company.


  • You will become an expert in your field.
  • Your customers will know what you’re good at and come to you for those services.
  • You can focus all of your energy on becoming the best at one thing.
  • Marketing becomes easier as your target market becomes more “defined”.


Some notable companies that have specialized and reaped the rewards are Apple with its technology products, Amazon with its online retail store, and Starbucks with its specialty coffee drinks.


In his book, Rice, Noodle, Fish, Anthony Bourdain discusses the Japanese approach to business and how they focus on one thing and get really good at it. He mentions how sushi chefs spend their entire lives mastering the art of sushi making, and how this dedication to a single craft has led to some of the best sushi in the world.


Bourdain goes on to say that Western businesses could learn a lot from the Japanese approach. He says that instead of trying to be all things to all people, we should focus on becoming experts in our field and delivering the best possible product or service. This strategy can deliver increased profit and a more successful business.


There are a few disadvantages to specializing in one area of business. You may become complacent and reluctant to try new things or you may miss out on opportunities in other or new markets.


Worried that there are already too many other businesses in the space you want to specialize in? There seems to be room for improvement in every industry. Walk into Sephora and you will find hundreds of lines of makeup – all selling the same products with different branding. What about vodka? Tito’s famously only sells one type of vodka – and nothing else. It doesn’t specialize in flavors or mixers, just vodka and as a result, the brand is well known for its quality product.


However, there are some ways to overcome these disadvantages.

1. Focus on becoming the best in your field. This means developing expertise in your area and offering top-quality products and services.

2. Market yourself as the go-to company for a certain type of product or service.

3. Stay up to date with current trends and changes in your industry. By doing so, you’ll be able to adapt your offerings as needed and continue to attract new customers.


If you are thinking about narrowing your focus in your business, talk to a trusted advisor or others who have gone down the uncertain road of specializing in one industry or product. 


You can talk to us too. Go to www.firststepsfinancial.com and click on the Let’s talk button to set up a time to continue the conversation.

Our Latest Insight

By Alisa McCabe • September 28, 2026
Article 2 ended with a question. What would you actually see first if this relationship started breaking down inside your business? Here is the answer. You would see five things. If you are like most owners reading this, you are already looking at two or three of them. None of the five announces itself as a communication problem. Each one shows up as friction inside your accounting systems, wearing a perfectly reasonable disguise. That is the difficulty. On the surface, none of these looks like a broken relationship. Each looks like something else entirely. A busy month. A tough quarter. A personality difference between two people who were never going to be friends anyway. Every one of them gets explained away the first time you see it. That is exactly what makes them expensive. This article does not fix any of it. Article 4 does that. The job here is naming what is already sitting in front of you. Most owners walk past these signs for years without recognizing what they are looking at.  ​ Part 3 of a 5-part series on the COO-Accounting relationship
By Alisa McCabe • September 21, 2026
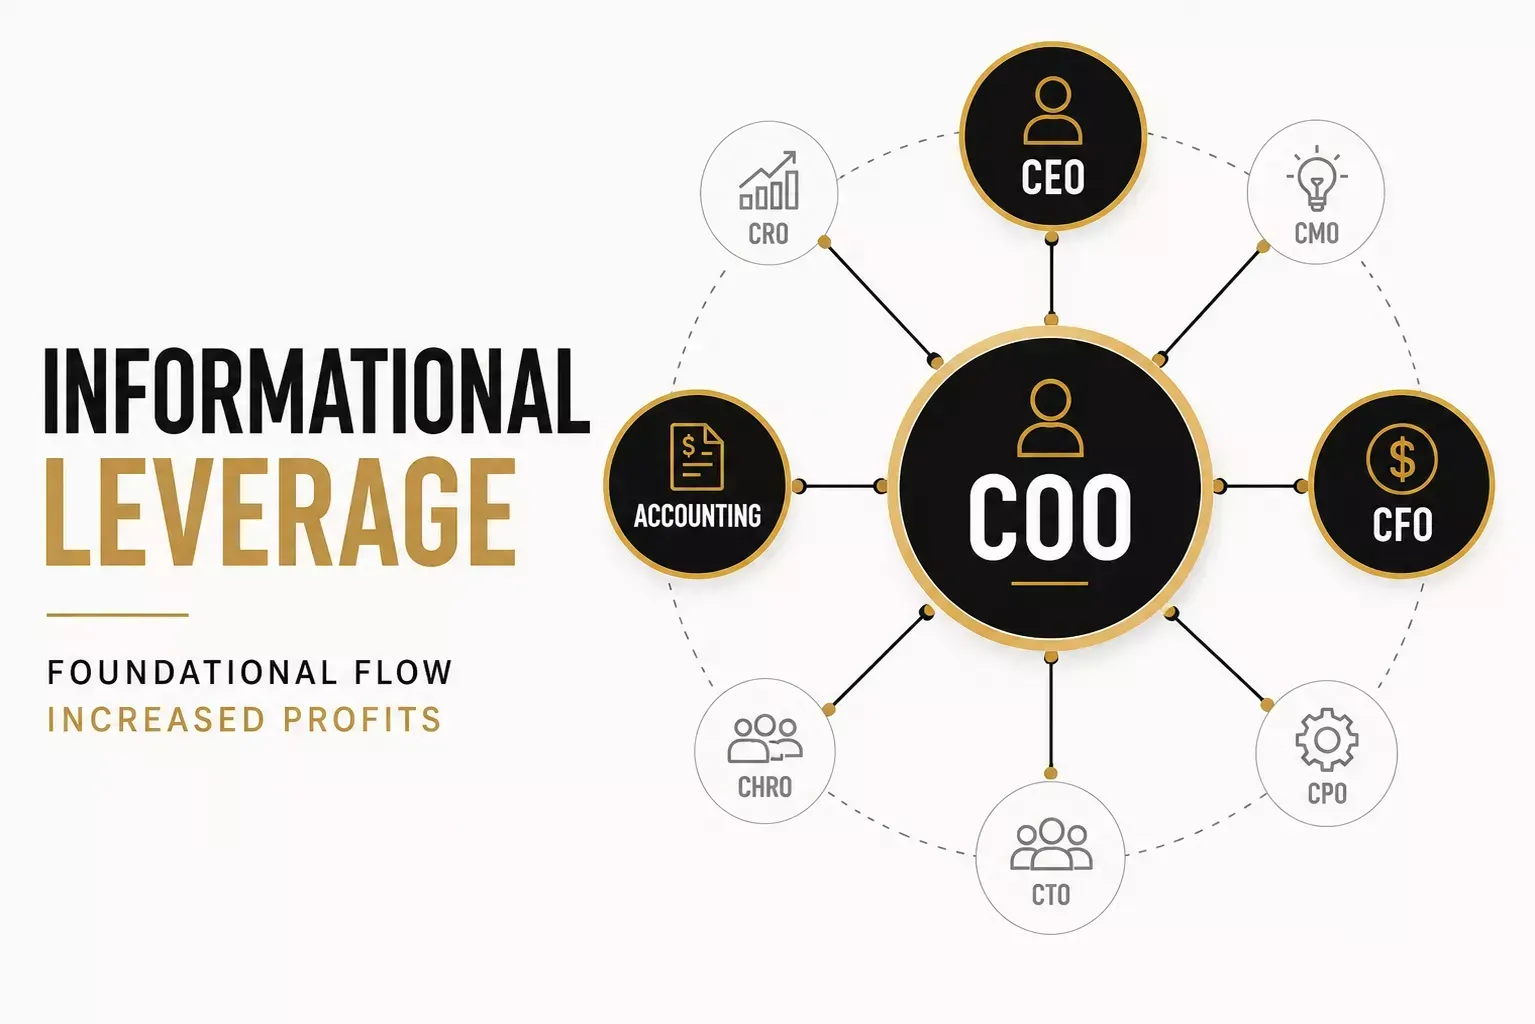
Article 1 ended with a question. When does your COO actually talk to Accounting before a decision gets made? How long did it take you to answer? Immediately? Minutes? Maybe you could not think of a single example. Bills get paid, projects keep moving, and financial reports show up. Nothing feels obviously broken, so you conclude everything is fine. If that question made you uncomfortable, you are not alone. Here is the part that keeps this problem alive. You only know what good looks like based on what you have already lived through. Most owners have never worked inside a business where Operations and Accounting were intentionally built to function together. So they measure their company against their own status quo. This article gives you a different reference point. You will see what the relationship looks like day to day, what rhythm it runs on, and five things you can check this week. None of it requires scrapping what you have built. The people are already in the building. The data already exists. What changes is how the pieces are arranged, and how much leverage you get out of the company you have right now.  ​ Part 2 of a 5-part series on the COO-Accounting relationship
By Alisa McCabe • September 14, 2026
"Accounting is a stick in the mud." "I'm not really sure what a COO does all day." "The CFO just plays around with their little Excel sheets." You have probably heard one of those lines. You may have thought one yourself. They sound like harmless office humor. They actually point to something expensive. In most growing service businesses, nobody has ever defined how operations and accounting work together. The people who produce your financial reports sit outside the very decisions those reports are meant to inform. That gap costs you every single month, quietly, in profit that should have been there.  ​ Part 1 of a 5-part series on the COO and Accounting relationship