Common Government Audits Every Business Should Know
Most Common Types of Government Audits
IRS Audits (Federal Tax Audits)
Correspondence Audit
- Conducted by mail.
- Usually focused on a specific item (e.g., missing 1099s, questionable deductions).
- Least invasive.
Office Audit
- Conducted at an IRS office.
- Involves a deeper look at specific parts of the return.
- Requires the business owner to bring documentation to support the claimed items.
Field Audit
- Conducted at the business location or the taxpayer’s accountant's office.
- Most comprehensive type.
- IRS examines books, records, operations, and business structure.
Common State Tax Audits
Income Tax Audit
- Similar to an IRS audit, but conducted by the state’s Department of Revenue or equivalent.
- Reviews state income tax returns and potential discrepancies.
Sales and Use Tax Audit
- Common for businesses that sell goods or taxable services.
- Ensures proper collection and remittance of sales tax.
- May also look at use tax for out-of-state purchases.
Payroll Tax Audit
- Examines state employment taxes (unemployment insurance, state withholding).
What Can Trigger These Types of Audits?
- Large discrepancies between reported income on state and federal returns
- Underreporting of income (e.g., cash-heavy business, missing 1099s)
- Consistently reporting losses over multiple years (especially if the business looks like a hobby)
- Discrepancies in payroll filings or failure to remit taxes
- Sudden spikes or drops in income without explanation
- Deposits in bank accounts exceed reported income
Tips to Avoid or Prepare for Audits
- Keep clear, accurate, and up-to-date financial records
- Be honest about your income and expenses
- File all required returns on time
- Classify workers correctly (W-2 vs. 1099)
- Maintain proper documentation for deductions and credits
- Stay compliant with state-specific tax and labor requirements
Our Latest Insight
Article 2 ended with a question. What would you actually see first if this relationship started breaking down inside your business? Here is the answer. You would see five things. If you are like most owners reading this, you are already looking at two or three of them. None of the five announces itself as a communication problem. Each one shows up as friction inside your accounting systems, wearing a perfectly reasonable disguise. That is the difficulty. On the surface, none of these looks like a broken relationship. Each looks like something else entirely. A busy month. A tough quarter. A personality difference between two people who were never going to be friends anyway. Every one of them gets explained away the first time you see it. That is exactly what makes them expensive. This article does not fix any of it. Article 4 does that. The job here is naming what is already sitting in front of you. Most owners walk past these signs for years without recognizing what they are looking at. Part 3 of a 5-part series on the COO-Accounting relationship
Article 1 ended with a question. When does your COO actually talk to Accounting before a decision gets made? How long did it take you to answer? Immediately? Minutes? Maybe you could not think of a single example. Bills get paid, projects keep moving, and financial reports show up. Nothing feels obviously broken, so you conclude everything is fine. If that question made you uncomfortable, you are not alone. Here is the part that keeps this problem alive. You only know what good looks like based on what you have already lived through. Most owners have never worked inside a business where Operations and Accounting were intentionally built to function together. So they measure their company against their own status quo. This article gives you a different reference point. You will see what the relationship looks like day to day, what rhythm it runs on, and five things you can check this week. None of it requires scrapping what you have built. The people are already in the building. The data already exists. What changes is how the pieces are arranged, and how much leverage you get out of the company you have right now. Part 2 of a 5-part series on the COO-Accounting relationship
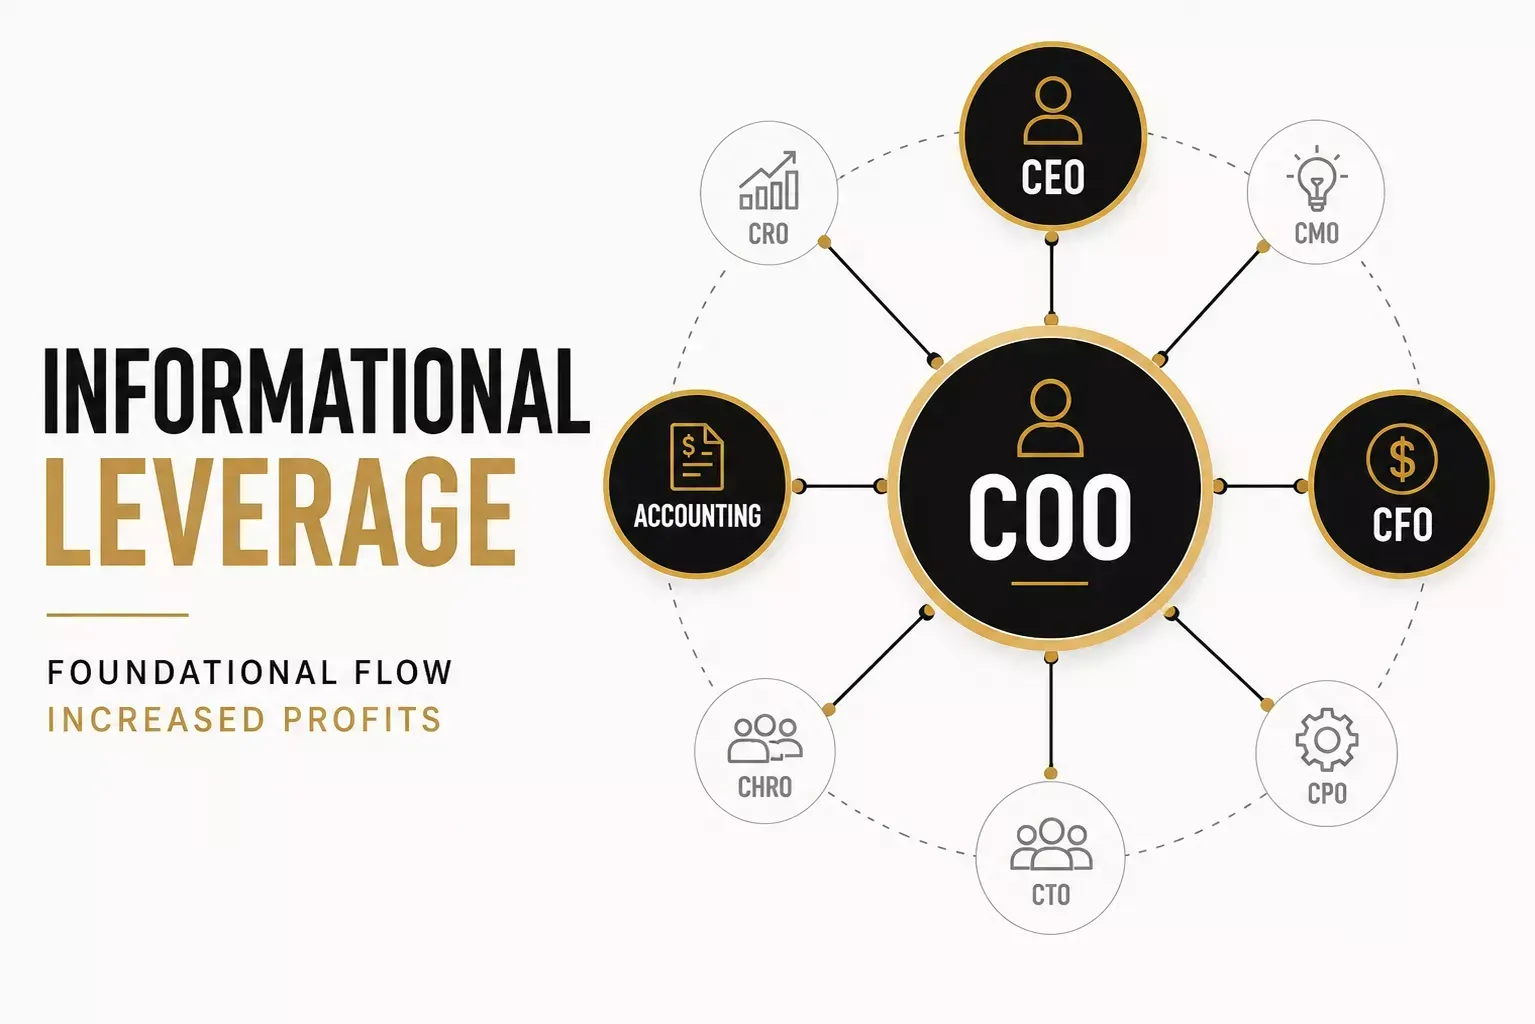
"Accounting is a stick in the mud." "I'm not really sure what a COO does all day." "The CFO just plays around with their little Excel sheets." You have probably heard one of those lines. You may have thought one yourself. They sound like harmless office humor. They actually point to something expensive. In most growing service businesses, nobody has ever defined how operations and accounting work together. The people who produce your financial reports sit outside the very decisions those reports are meant to inform. That gap costs you every single month, quietly, in profit that should have been there. Part 1 of a 5-part series on the COO and Accounting relationship